Buy a Home in Annandale, VA with Less Down
Annandale VA Real Estate, Down Payment Options, Home Buying
Can I Buy a Home in Annandale, VA With Less Than 20% Down?
The old “20% down or don’t buy” rule is outdated—and in Annandale’s fast‑moving market, it can quietly cost you years of equity and thousands of dollars in appreciation. If you’re waiting to hit that magic 20% number, you may be waiting while other buyers move into the very homes you want.
The Bold Truth: You Don’t Need 20% Down in Annandale
In Annandale—and across Fairfax County—many buyers are quietly purchasing homes with 3%–5% down, and some with 0% down. The difference is not that they’re wealthier; it’s that they’re working with lenders and agents who know today’s loan programs and how to align them with clear financial goals and real market conditions, not myths from decades ago.
Your Down Payment Options in Annandale, VA
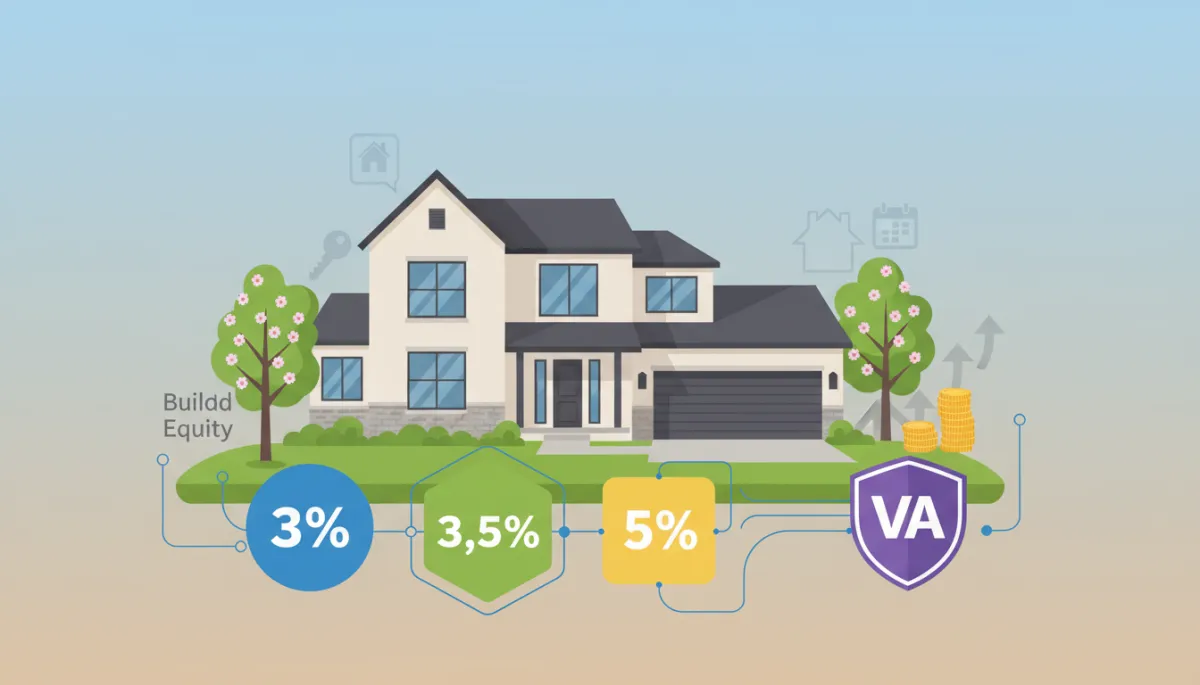
Let’s break down the most common low-down-payment options we see buyers using right now in and around Annandale.
3% Down Conventional Loans
With strong credit and stable income, many buyers qualify for 3% down conventional loans. On a $600,000 Annandale home, that’s $18,000—not $120,000. These loans often come with flexible terms and, once your equity grows, you can remove private mortgage insurance (PMI) down the road. For buyers who’ve been diligently saving but haven’t hit 20%, this is often the key that finally unlocks the front door.
3.5% Down FHA Loans
FHA loans typically allow you to buy with just 3.5% down, often with more flexible credit and debt‑to‑income requirements than conventional financing (NerdWallet, Bankrate). For many Annandale buyers, especially first‑timers, FHA is the bridge between “I wish I could buy” and “I just got the keys.” The trade‑off: you’ll pay mortgage insurance premiums for longer, so it’s crucial to weigh that cost against the benefit of getting in sooner.
5% Down Conventional Loans
If you can stretch to 5% down, you may unlock even better conventional loan pricing and lower mortgage insurance costs. For buyers with solid income who want a little more room in their monthly budget, 5% down can be a powerful sweet spot—still far below 20%, but often with more favorable terms than ultra‑low‑down options.
VA Loans: Potentially 0% Down for Eligible Buyers
If you’re active‑duty military, a Veteran, Guard/Reserve, or a qualifying surviving spouse, a VA loan can be a game‑changer in Annandale. With a valid Certificate of Eligibility and sufficient income, many buyers can purchase with no down payment and no monthly PMI (VA.gov). In a high‑cost area like Fairfax County, that can mean stepping into a home years earlier than you thought possible while keeping more cash in your pocket.
How Buyers Are Actually Purchasing Annandale Homes With Less Than 20% Down
In real life—not on social media—Annandale buyers are stacking smart strategies: pairing low‑down‑payment loans with Fairfax County and Virginia Housing assistance, grants, or second‑mortgage programs that help cover down payment and closing costs. Some Virginia Housing options can reduce buyer cash to as little as 1% of the purchase price when combined with grants, while Fairfax County’s deferred shared‑equity loans can help first‑time buyers bridge the gap without monthly payments (Fairfax County, Virginia Housing).
Many Annandale buyers close with 3–5% down once the right loan plan is in place.
The Big Upside: Why Buying Sooner Can Be Smarter
In a strong Northern Virginia market, waiting for 20% down can mean chasing a moving target. While you save, prices and rents can climb. By using a smaller down payment, you can:
Start building equity earlier as your loan balance shrinks and Annandale home values potentially rise.
Lock in housing costs instead of riding the annual rent‑increase roller coaster.
Maintain critical cash reserves for emergencies, repairs, or future opportunities instead of draining every dollar into the down payment.
The Trade‑Offs: Mortgage Insurance and Higher Monthly Costs
Let’s be bold and honest: buying with less than 20% down usually means mortgage insurance and a higher monthly payment than if you put more down. FHA loans require upfront and annual mortgage insurance premiums; conventional loans with under 20% down carry PMI; VA loans often include a funding fee (unless you’re exempt). These are real costs, and they matter.
But here’s the key question The Mike Webb Team asks every buyer: Do these added costs still make sense when you factor in your timeline, rent, tax benefits, and expected appreciation? For many Annandale families, the answer is a confident yes—especially when the alternative is renting for years while prices climb.
Real‑Life Scenarios From Annandale Buyers
Scenario 1: The “We’ll Wait for 20%” Couple
A young couple in Annandale planned to wait three more years to save 20% for a townhouse. In those three years, similar townhomes rose by tens of thousands of dollars. When they finally hit their savings goal, the price point they wanted had moved out of reach. Had they used a 3% or 5% down conventional loan earlier, they could have been building equity instead of chasing prices.
Scenario 2: The Veteran Who Thought He Needed 10% Down
A Veteran renting in Annandale assumed he needed at least 10% down. After an early consultation, a lender confirmed he qualified for a VA loan with 0% down. He kept his savings intact, bought a home near work, and now enjoys stable payments instead of rising rent—all because he asked the question sooner.
Common Mistakes Annandale Buyers Make With Down Payments
Fixating on the 20% rule instead of running the numbers on today’s loan programs and local appreciation.
Draining every dollar into the down payment and leaving no cash reserves for repairs, job changes, or life surprises.
Ignoring assistance programs from Fairfax County, Virginia Housing, or state DPA options that could dramatically lower cash needed at closing.
Waiting to talk to a lender until they “feel ready,” instead of getting clarity early and using that information to build a strategic savings plan.
Start With Your Financial Goals and Market Conditions—Not a Rule of Thumb
The right down payment for you is not a number from a blog or a TikTok clip; it’s the number that fits your financial goals, your risk comfort, and today’s Annandale market conditions. Are you planning to stay in the home for five years or fifteen? How secure is your income? What are rents doing in your area? How quickly are homes like the one you want appreciating? These are the questions that matter.
Why Early Lender Consultation and Personalized Planning Are Non‑Negotiable
Bold move number one: talk to a trusted local lender early—long before you’re “ready” to buy. A good lender can map out exactly what 3%, 3.5%, 5%, or even 0% down would look like for you: monthly payment, cash at closing, mortgage insurance, and how different scenarios align with your goals. That clarity is power.
At the same time, work with an Annandale‑focused real estate team that treats this as more than a transaction. The Mike Webb Team helps you build a personalized plan—from exploring assistance programs and loan types to choosing neighborhoods and home styles that match both your budget and your long‑term vision. Our job is to replace guesswork with confident, informed decisions.
Ready to Explore Less‑Than‑20% Down Options in Annandale?
You do not have to wait for 20% down to own a home in Annandale, VA. You do, however, need a clear plan, the right loan strategy, and advisors who will tell you the truth about both the benefits and the trade‑offs. If you’re ready to stop wondering and start planning, The Mike Webb Team is here to help you step into your next chapter with confidence, clarity, and less stress.