Buyer Closing Costs in Virginia Explained
closing costs, home buyers, Virginia real estate, Loan Estimate, Closing Disclosure, Arlington VA, first-time buyer
What Are Buyer Closing Costs in Virginia, and When Do I See the Numbers?
Closing costs are the fees you pay to finish a home purchase, in addition to your down payment. Your lender must give you a Closing Disclosure three business days before closing, so you can check the numbers.
What are closing costs for a buyer?
Closing costs are the fees you pay to finish a home purchase, in addition to your down payment. Your lender must give you a Closing Disclosure three business days before closing, so you can check the numbers.
We never want a buyer surprised at the table. Here is what to expect, with no guessing at dollar amounts, because every loan is different.
The Mike Webb Team (Mike and Claudia Webb, RE/MAX Allegiance) helps homeowners in Arlington, Northern Virginia, Maryland, and Washington, DC get their homes ready to sell and sold.
What are closing costs for a buyer?
Closing costs are the fees you pay to finish a home purchase, in addition to your down payment. Your lender must give you a Closing Disclosure three business days before closing, so you can check the numbers.
What is in closing costs?
Common items include:
Lender fees. Charges for making the loan.
Title costs. A title search and title insurance protect you and your lender.
Settlement fees. The company that handles the closing charges for its work.
Recording and government charges. For recording the deed and loan.
Prepaid items. Such as homeowner's insurance and some taxes, often paid at closing.
Discount points, if you choose to pay them to lower your rate.
Your own list may differ. Ask your lender for a full list early.
What are discount points?
According to the Consumer Financial Protection Bureau, one point equals one percent of the loan amount. You pay points at closing, and they lower your interest rate. Points appear on page 2 of your Loan Estimate and Closing Disclosure.
When do I see the real numbers?
Two papers matter:
The Loan Estimate. You get it after you apply. It is an early look at costs.
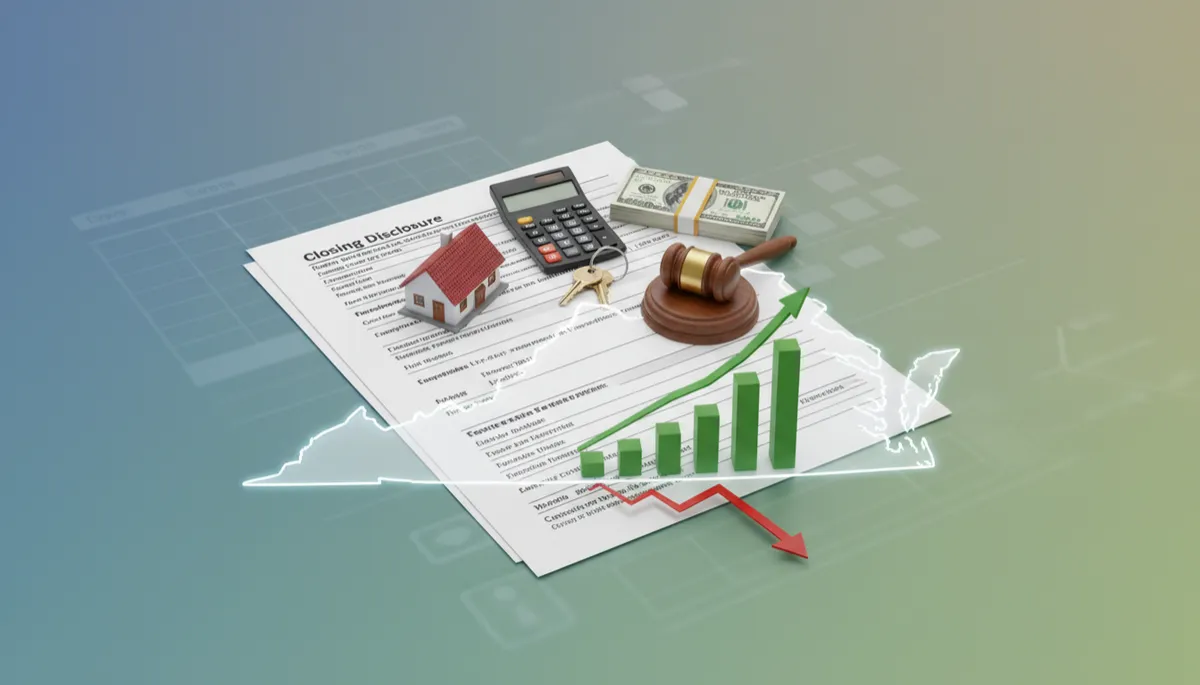
The Closing Disclosure. Your lender must give it to you "three business days before your scheduled closing," says the CFPB. It shows your loan terms, monthly payment, escrow, and closing costs.
Compare the two. If something grew or is new, ask why.
Can the seller help?
Sometimes a seller agrees to help with some of your costs as part of the deal. That is a negotiating point, and it depends on the loan and the contract. We help you decide whether to ask.
How much cash should I plan for?
Ask your lender for an estimate based on your loan, then add a cushion. The down payment, the deposit, and the closing costs are all separate lines.
FAQ
Can I roll closing costs into my loan?
Sometimes, depending on the loan. Ask your lender.
Do I pay everything on closing day?
Some costs, such as the inspection, are paid earlier. Your agent will list them.
Who do I ask if a fee looks wrong?
Ask your lender or settlement agent right away, and tell us too.
Call or text The Mike Webb Team at 703-350-3884 or visit claudiawebb.com.
The Mike Webb Team, RE/MAX Allegiance. Arlington, Virginia. Equal Housing Opportunity.