Buying a Home in Manassas Park: Costs & Tips
Manassas Park Real Estate, Home Buying Costs, Virginia Homebuyer Assistance, Closing Costs Estimate, Down Payment Options, First-time Homebuyer Guide
How Much Money Do I Need to Buy a House in Manassas Park, VA?
If you are considering a move in or around Manassas Park, understanding the true cost of buying a home is one of the most important steps you can take. As a trusted local real estate team, The Mike Webb Team is committed to giving you clear, practical numbers so you can plan with confidence and less stress.
What Homes Cost in Manassas Park Today
Before you can estimate how much money you will need, it helps to know what homes are actually selling for right now. As of mid‑2026, most Manassas Park Real Estate listings fall in the mid‑$400,000s to just under $500,000, depending on size, condition, and whether you are looking at a condo, townhome, or single‑family home.
Recent data shows:
Zillow reports an average home value of about $467,000 in Manassas Park, with a median listing price around $480,000 (June 2026).
Realtor.com lists a median sold price close to $467,000 and a median listing price around $485,000, with homes spending about 26 days on the market.
A March 2026 regional report shows a median sales price of about $460,000 for closed sales in Manassas Park, up 7% year‑over‑year.
In practical terms, if you are planning to buy, it is wise to budget around $460,000 to $485,000 as a typical purchase price range. Condos and townhomes may be somewhat lower, while updated single‑family homes may be higher. The Mike Webb Team can help you refine this range based on your preferred neighborhood, property type, and timing.
Breaking Down Total Home Buying Costs
Many buyers focus on the purchase price and monthly payment, but the full picture of home-buying costs in Manassas Park includes several components you will need to prepare for. At a high level, you should plan for:
Your down payment
Closing costs (fees and prepaid items due at settlement)
Moving and immediate setup expenses (moving company, deposits, initial repairs, and furnishings)
Let us walk through what these look like for a typical Manassas Park home priced at $475,000, which is close to today’s median listing price.
Example Budget on a $475,000 Home
Cost Category Typical Range Estimated Amount on $475,000 Down payment (3%–20%+) $14,250 – $95,000+ Depends on loan type and Down Payment Options Buyer closing costs 2%–5% of price About $9,500 – $23,750 Moving & immediate needs Varies widely Commonly $2,000 – $8,000+
The good news is that you rarely have to cover all of this alone. With the right loan program, Virginia Homebuyer Assistance, and possible seller credits, your upfront cash requirement can be significantly lower than you might expect. The Mike Webb Team regularly helps buyers structure offers and financing to keep cash at closing as manageable as possible, while still protecting long‑term affordability.
Down Payment Options for Manassas Park Buyers
There is no single “right” down payment. The best choice depends on your savings, income stability, and how long you plan to stay in the home. Here are the most common Down Payment Options we see in Manassas Park Real Estate transactions today:
Conventional Loans (3%–20%+ Down)
Many buyers use a conventional loan, which can allow as little as 3% down for qualified borrowers. On a $475,000 home, that is:
3% down: approximately $14,250
5% down: approximately $23,750
20% down: approximately $95,000
With less than 20% down, you will typically pay private mortgage insurance (PMI), which increases your monthly payment but allows you to buy sooner. As your equity grows, PMI can often be removed later. The Mike Webb Team can help you compare scenarios so you can see the trade‑offs clearly before you decide.
FHA Loans (3.5% Down)
FHA loans are popular with first‑time buyers because they allow lower credit scores and a down payment as low as 3.5%. On a $475,000 purchase, that is about $16,625. FHA loans do require mortgage insurance for the life of the loan or until you refinance, but they can be an excellent option if you are building credit or have limited savings.
VA and USDA Loans (0% Down for Eligible Buyers)
If you are an eligible veteran, active‑duty service member, or qualifying surviving spouse, a VA loan may allow you to purchase with no down payment. Certain USDA loans can also offer zero‑down options in designated areas. These programs can dramatically reduce upfront cash needs, though there may be funding fees or other program‑specific costs to consider.
Combining Loans with Grants and Assistance
In Virginia, you can often layer your primary mortgage with state or local Virginia Homebuyer Assistance programs. These may come in the form of grants, deferred loans, or second mortgages that cover some or all of your down payment and closing costs. We will explore these in more detail below, but it is important to know that you may not need to rely solely on your own savings to reach your down payment goal.
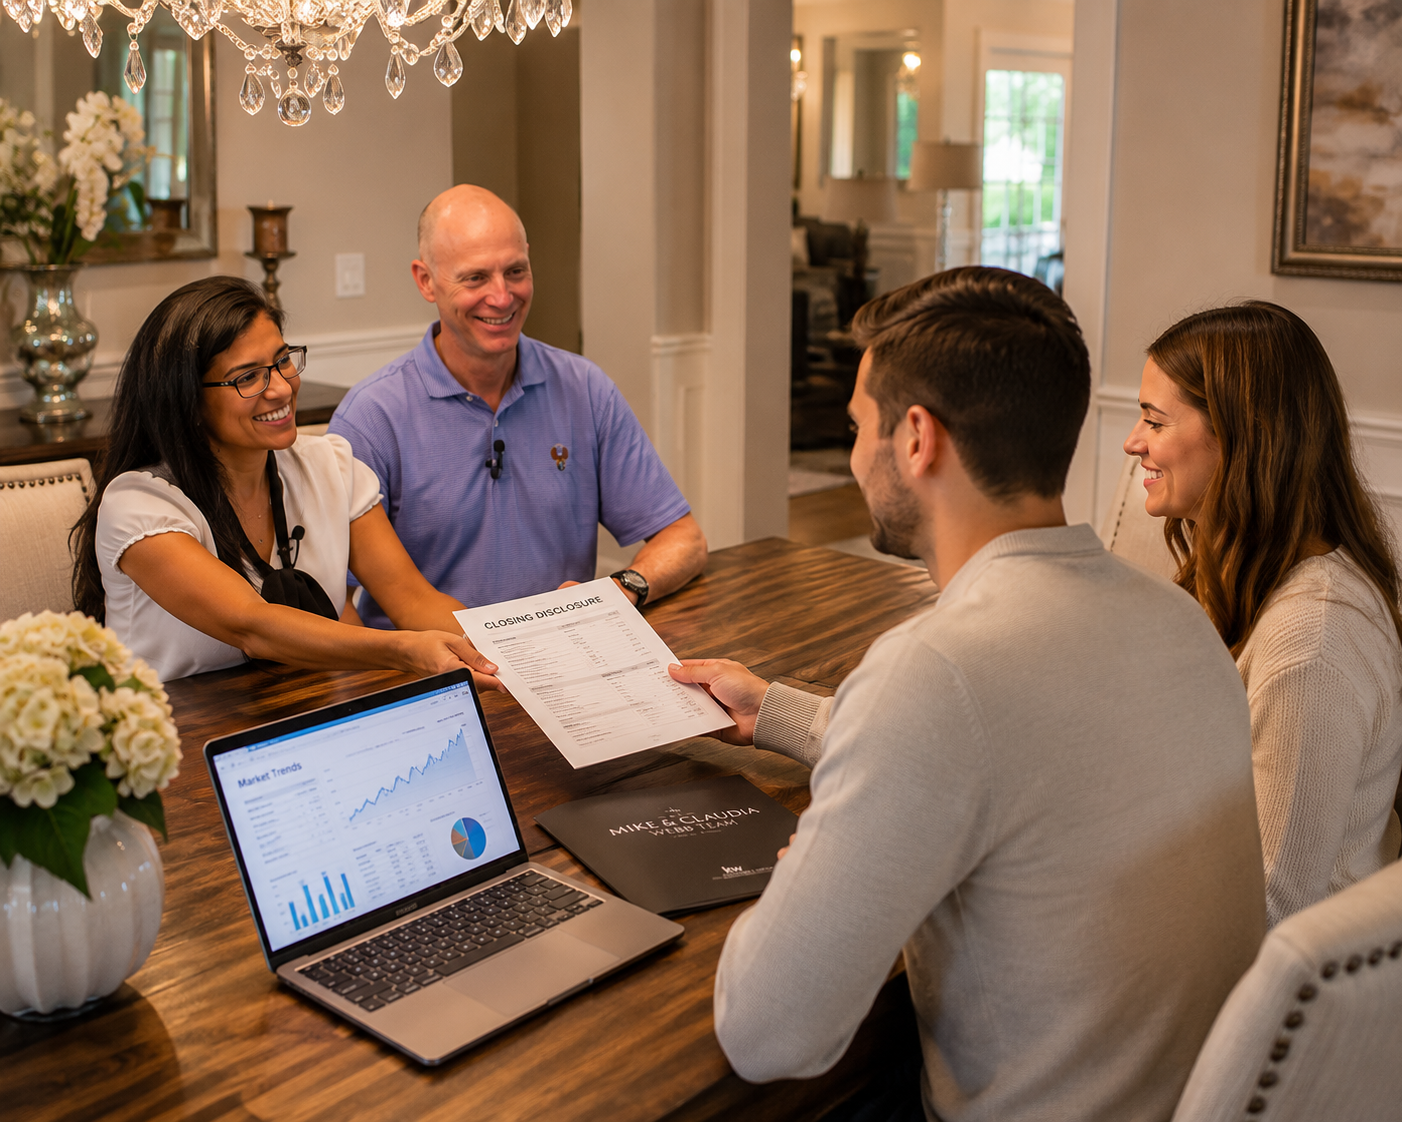
Reviewing your down payment and assistance options early keeps surprises off the closing table.
Closing Costs Estimate in Manassas Park, VA
In addition to your down payment, you will pay a series of fees and prepaid expenses at settlement. In Virginia, buyer closing costs typically range from 2% to 5% of the purchase price, according to multiple consumer finance sources. For a $475,000 home, that means roughly $9,500 to $23,750 in closing costs, though many buyers land toward the lower end of that range.
Typical Buyer Closing Cost Line Items
Loan origination fees – Often 0.5% to 1% of the loan amount, paid to your lender for processing and underwriting your mortgage.
Appraisal – Typically $300 to $500 to confirm the property’s value for your lender.
Home inspection – Commonly $300 to $500, paid directly to an inspector you choose. This is usually paid before closing, but it is part of your overall home-buying costs.
Title search and title insurance – Approximately $700 to $1,000 combined, to ensure clear ownership and protect against title defects.
Attorney or settlement fees – Often $500 to $1,000, depending on the settlement company and the complexity of the transaction.
Recording fees – Generally $100 to $200, paid to the city or county to record your deed and mortgage.
Transfer taxes and government charges – In Virginia, transfer taxes and related fees often total around 1% of the purchase price, though the exact split between buyer and seller can vary by contract and local practice.
Prepaid items – These include your first year of homeowners insurance, several months of property taxes, and prepaid interest from closing until your first mortgage payment. These can add several thousand dollars to your Closing Costs Estimate.
💡 Pro Tip from The Mike Webb Team: Ask your lender for an upfront Loan Estimate early in the process. We will review it with you line by line, so you know exactly what each cost covers and where assistance or seller credits might reduce your out‑of‑pocket amount.
Virginia Homebuyer Assistance: Programs You Should Know
One of the most encouraging parts of buying in Virginia is the range of Virginia Homebuyer Assistance programs designed to help with down payments and closing costs. Many Manassas Park buyers qualify for at least one of these options, and sometimes more than one can be combined. Here is an overview of the most relevant programs as of mid‑2026. Program guidelines can change, so always confirm current details with your lender and housing counselor.
DHCD Homeownership Down Payment and Closing Cost Assistance
The Virginia Department of Housing & Community Development (DHCD) offers the HOMEownership Down Payment and Closing Cost Assistance (DPA) Program. This program provides a deferred second trust loan to eligible first‑time buyers with incomes up to 80% of Area Median Income (AMI).
Assistance can cover 10% or 15% of the sales price (depending on the region), plus up to $2,500 for closing costs, with a maximum of $40,000.
The loan is deferred, meaning no monthly payments and typically no interest as long as you meet the occupancy requirements and program terms.
On a $475,000 home, a 10% DPA award could potentially provide up to $47,500 in assistance (subject to the $40,000 cap and current guidelines), dramatically reducing the cash you need to bring to closing. This can be life‑changing for many first‑time buyers in Manassas Park.
Virginia Pilot DPA Program
For buyers with lower incomes, the Virginia Pilot DPA Program targets first‑time buyers earning up to 60% of AMI and can offer up to $50,000 in deferred assistance. If you qualify, this program can cover a substantial portion of your down payment and closing costs, especially when combined with a low‑down‑payment first mortgage.
Virginia Housing Grants and Second Mortgages
Virginia Housing (formerly VHDA) offers several key resources that many Manassas Park buyers use:
Down Payment Assistance (DPA) Grant – A true grant (no repayment) covering 2% of the sales price with bond conventional loans or 2.5% with bond FHA loans. This can reduce your required down payment to as little as 1% of the purchase price, subject to income and price limits.
Closing Cost Assistance (CCA) Grant – Helps cover closing costs for eligible buyers using Rural Housing Service (RHS) or VA bond loans, again with no repayment required.
Plus Second Mortgage – A secondary loan that can be paired with a Virginia Housing first mortgage to cover the remaining down payment or closing costs for buyers who do not qualify for grants or are not first‑time buyers.
Virginia Housing also offers 30‑year fixed‑rate loans, some with zero down payment options and flexible credit requirements, making ownership more accessible for a wide range of buyers.
Local and Nonprofit Assistance for Manassas Park Buyers
Because Manassas Park is part of the greater Prince William area, local programs may also be available to you:
Prince William Area First Time Homebuyers Program (FTHB) – Serves low‑ and moderate‑income first‑time buyers (generally up to 80% of AMI) who live or work in Prince William County, Manassas, or Manassas Park. This program provides down payment and closing cost assistance via loans and requires HUD‑certified homebuyer education. Funds are limited and often awarded on a first‑come, first‑served basis.
VHCDC Home Ownership Assistance Program (HOAP) – A nonprofit‑led program that, for a modest enrollment fee, connects buyers with multiple resources, including DPA/CCA grants, rate‑reduction programs, and counseling. This can be especially valuable for buyers who want ongoing support and education throughout the process.
📌 Key Takeaway: Many Manassas Park buyers qualify for thousands, and sometimes tens of thousands, of dollars in assistance. The Mike Webb Team works closely with local lenders and housing counselors to help you identify every program you are eligible for, so you are not leaving money on the table.
First-Time Homebuyer Guide: Step-by-Step in Manassas Park
Buying your first home can feel overwhelming, but with the right guidance, it becomes a series of clear, manageable steps. This First-time Homebuyer Guide is tailored specifically to Manassas Park and Northern Virginia, reflecting how transactions actually unfold here in 2026.
Step 1: Clarify Your Budget and Timeframe
Start by reviewing your income, current debts, and savings. Decide how much you are comfortable paying each month and how much cash you can reasonably allocate to your down payment and closing costs, while still keeping an emergency fund. In Manassas Park, where typical prices hover around $460,000–$485,000, this will help you and your lender target a realistic price range from the beginning.
Step 2: Talk with a Local Lender and Get Pre‑Approved
A strong pre‑approval is essential in today’s market. A local lender familiar with Manassas Park and Virginia programs can:
Review your credit and income to determine what you qualify for.
Recommend loan types and down payment options that fit your goals.
Identify which Virginia Homebuyer Assistance programs you may be eligible for and how they can be combined.
The Mike Webb Team can introduce you to reputable, experienced lenders who understand the local landscape and share our commitment to clarity and professionalism.
Step 3: Complete Homebuyer Education (If Required)
Many assistance programs, including DHCD and Virginia Housing offerings, require a HUD‑certified homebuyer education course. These classes explain budgeting, credit, mortgages, and the closing process in plain language. Even when not required, we strongly recommend them; they complement the one‑on‑one guidance you receive from our team and your lender and help you feel more confident in every decision.
Step 4: Start Your Home Search with a Clear Strategy
With pre‑approval in hand, you are ready to tour homes. In Manassas Park, inventory is still relatively tight, with fewer than 50 active listings at a time in recent reports. That makes it important to:
Prioritize your needs (bedrooms, commute, school preferences, parking, outdoor space).
Be realistic about trade‑offs between price, condition, and location.
Move quickly but thoughtfully when a good fit appears; homes are still selling close to list price on average.
Our role as your advisors is to provide honest, data‑driven insights into each property’s value and resale potential, so your first home is also a sound long‑term investment.
Step 5: Make an Offer and Negotiate with Confidence
When you are ready to make an offer, we will help you structure terms that balance competitiveness with financial protection. This may include:
Requesting seller credits toward your Closing Costs Estimate, where appropriate and realistic in the current market.
Including inspection and financing contingencies to protect your deposit.
Coordinating timelines with your lender and any assistance programs so that all funds are ready by closing.
Step 6: Complete Inspections, Appraisal, and Final Loan Approval
After your offer is accepted, you will schedule your home inspection, and your lender will order the appraisal. This is also when you will finalize your homeowners insurance and provide any remaining documents for underwriting. We stay closely involved during this stage, helping you interpret inspection findings, negotiate repairs or credits when appropriate, and keep the transaction on track toward closing.
Step 7: Review Your Final Numbers and Close
A few days before settlement, you will receive a Closing Disclosure from your lender. This document outlines your final loan terms and all closing costs. Together with your lender and The Mike Webb Team, you will confirm:
Your exact cash to close (after accounting for assistance funds and any seller credits).
How your down payment and closing costs are being covered (personal funds, grants, second mortgages, etc.).
When and how to wire your funds safely to the settlement company.
On closing day, you will sign your documents, receive your keys, and officially become a homeowner in Manassas Park. Our relationship does not end there; we remain a resource for questions about maintenance, future upgrades, and long‑term planning, including when it might make sense to sell and move forward to your next chapter.
So, How Much Money Do You Really Need?
Because there are so many variables—loan type, assistance programs, seller credits, and property choice—it is impossible to give a single number that fits every buyer. However, for a typical first‑time buyer purchasing around $475,000 in Manassas Park, a realistic starting point might look like this:
Down payment: $10,000–$25,000 out of pocket, after factoring in grants or deferred assistance (some buyers may need more, others less, depending on eligibility).
Closing costs: $5,000–$15,000 out of pocket, again depending on lender credits, seller contributions, and assistance programs.
Moving and setup: $2,000–$8,000+ for movers, deposits, and immediate needs.
Some well‑qualified buyers with strong savings may prefer to put more down to lower their monthly payment and avoid mortgage insurance. Others, especially first‑time buyers using Virginia Homebuyer Assistance, may be able to purchase with a far smaller cash investment than they assumed. The key is to build a customized plan based on your situation, rather than to guess.
Partnering with The Mike Webb Team
Buying a home in Manassas Park is a major step, both financially and personally. Our mission at The Mike Webb Team is to give you the clarity, confidence, and expert guidance you need to move forward without unnecessary stress. We combine up‑to‑date market knowledge, careful attention to your goals, and a warm, conversational approach that keeps you informed at every turn—without pressure or jargon.
Whether you are months away from your first purchase or ready to start touring homes this week, we are here to help you understand your numbers, explore your Down Payment Options, unlock available assistance, and find the right home at the right time. If you would like a personalized estimate of your Home Buying Costs in Manassas Park—including a detailed Closing Costs Estimate and a review of all relevant Virginia Homebuyer Assistance programs—reach out to The Mike Webb Team. Together, we will build a clear, realistic plan to get you home.